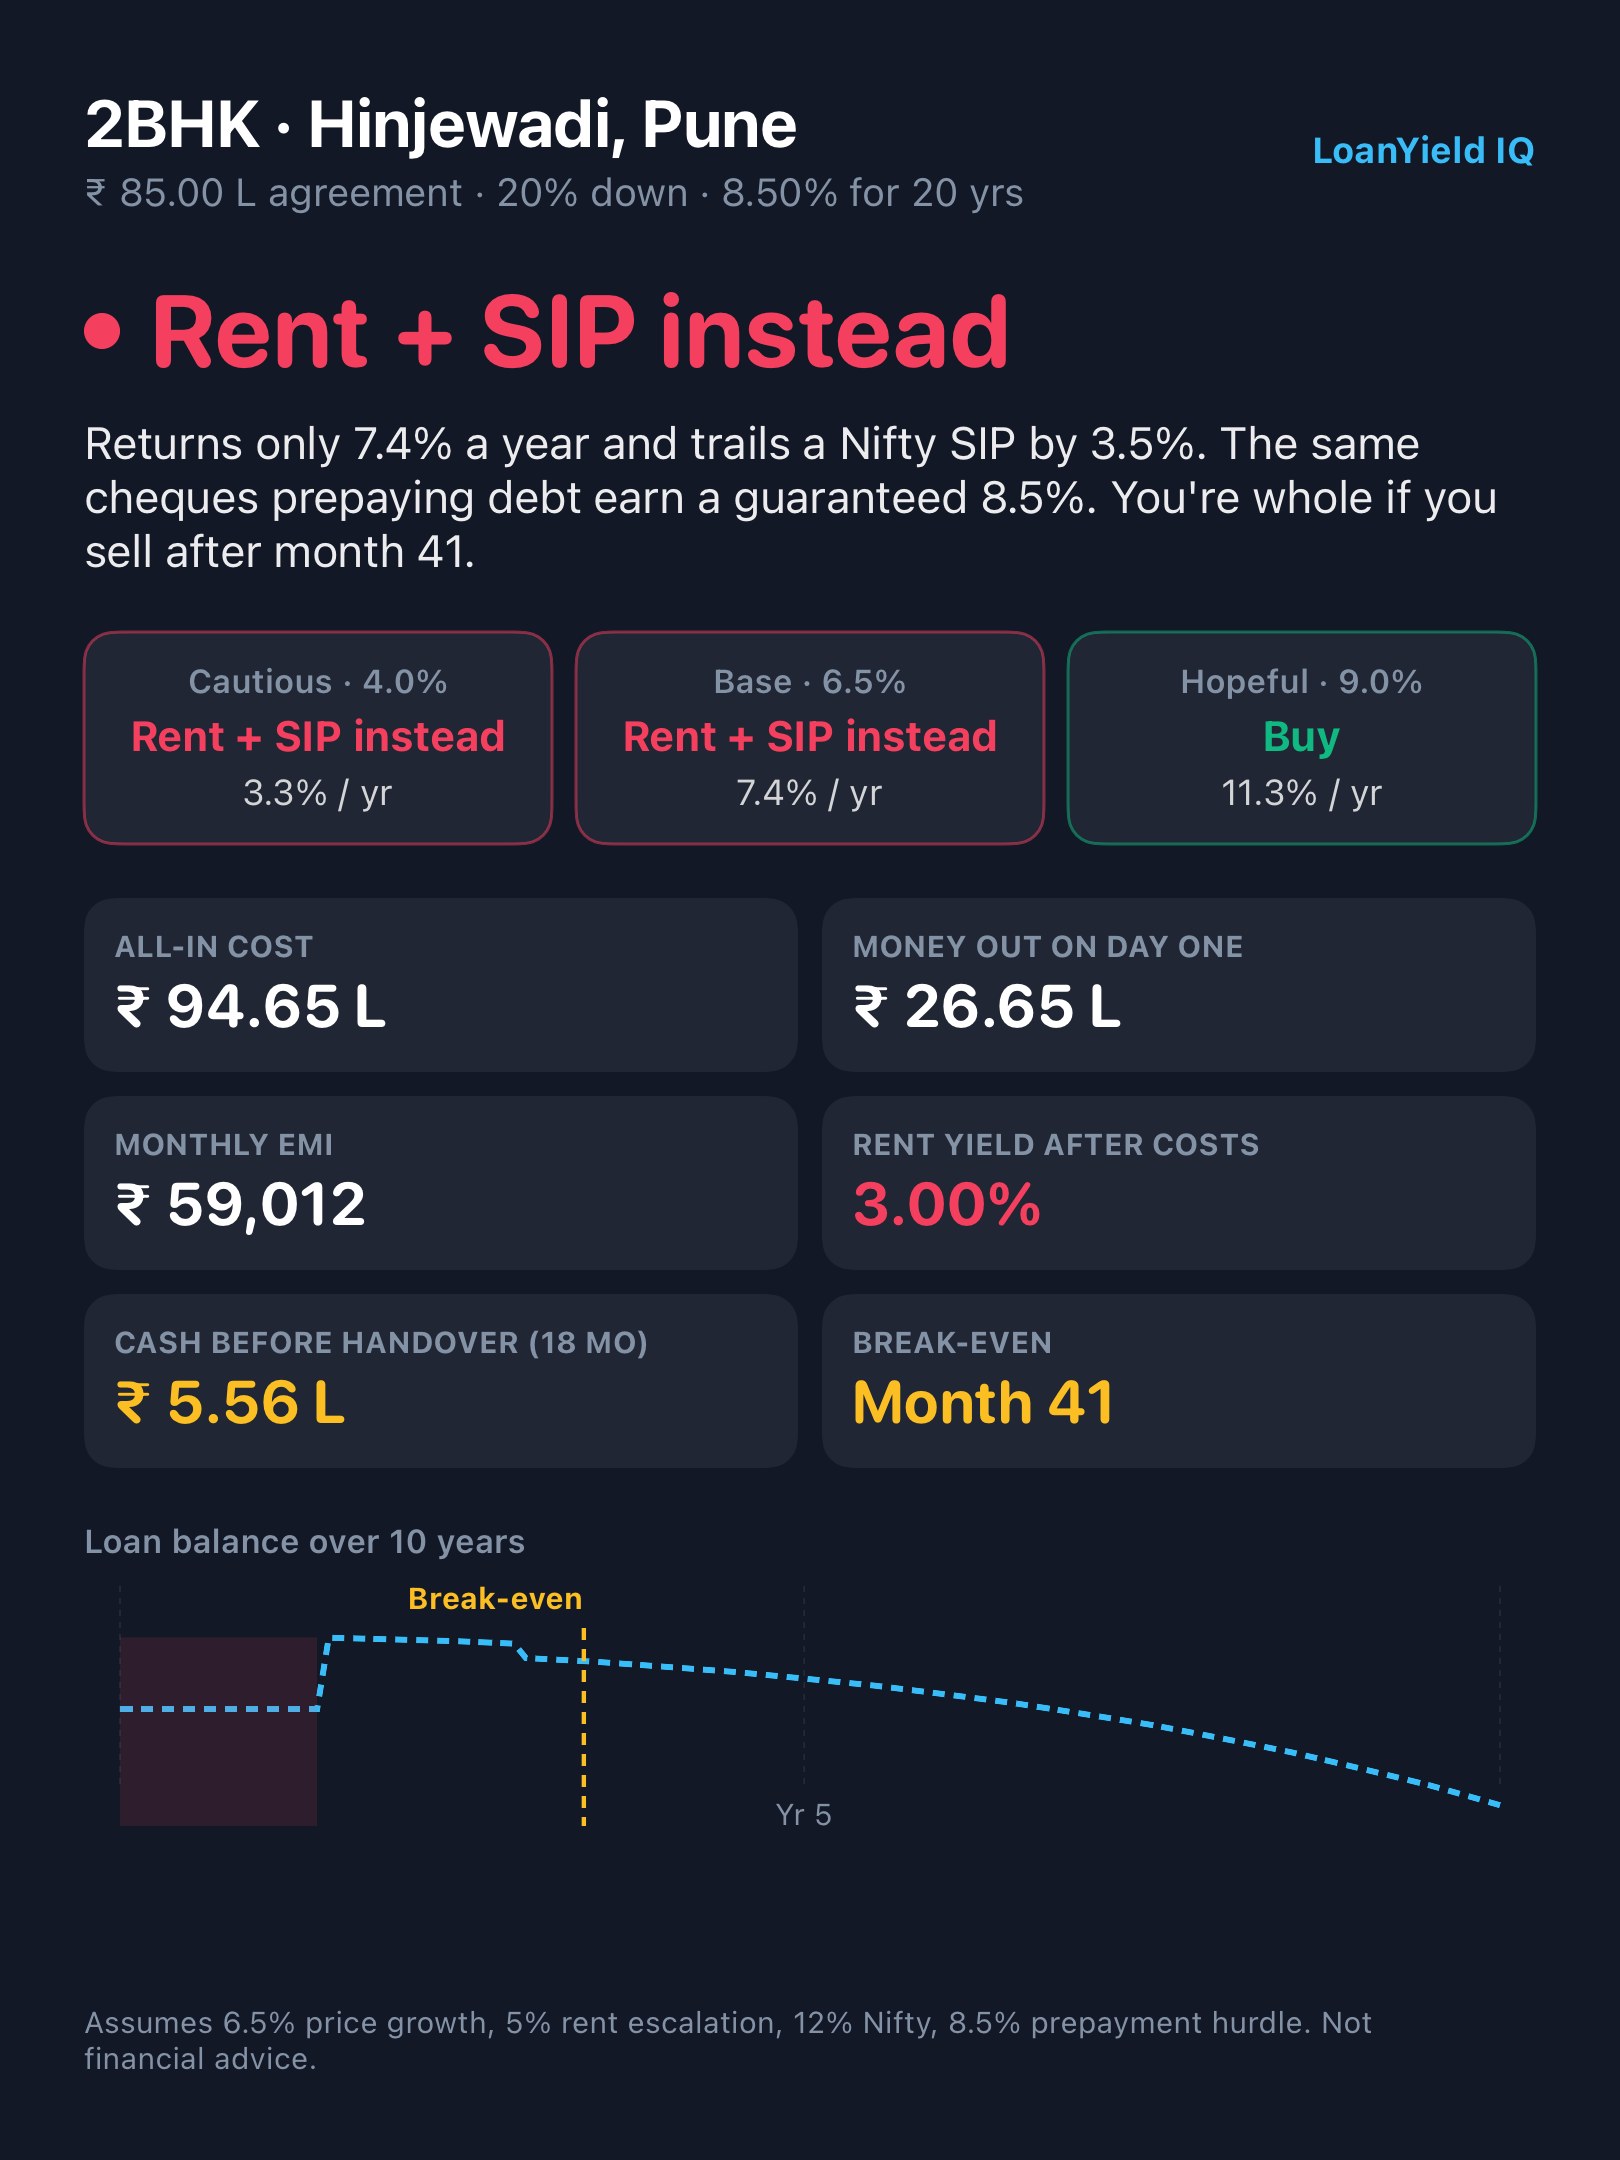
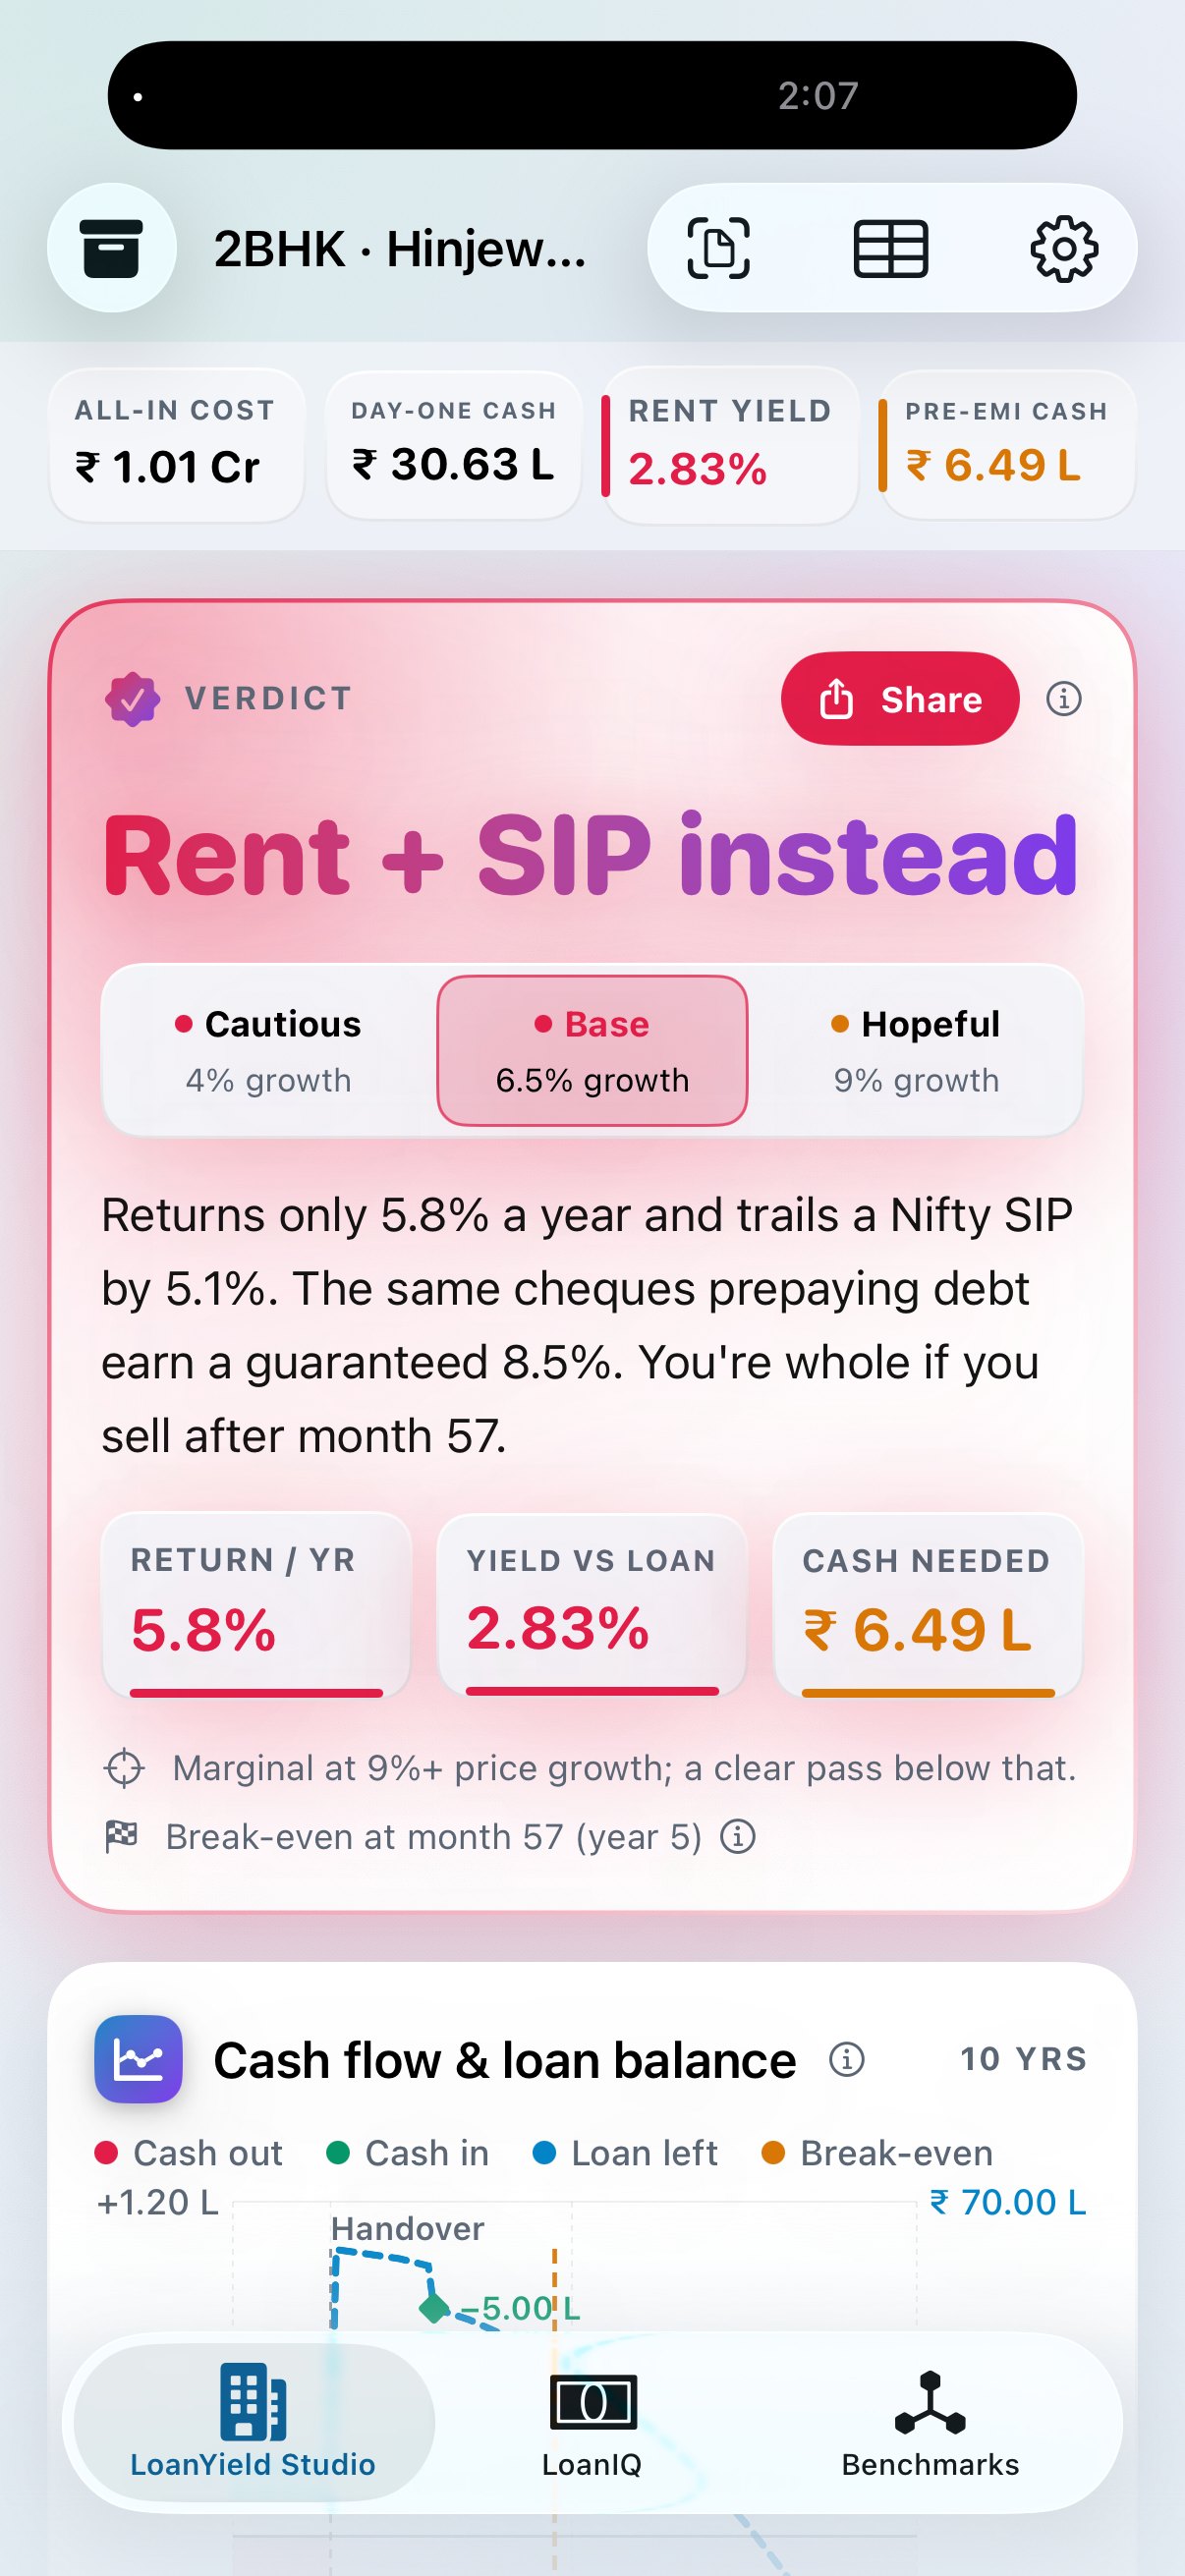
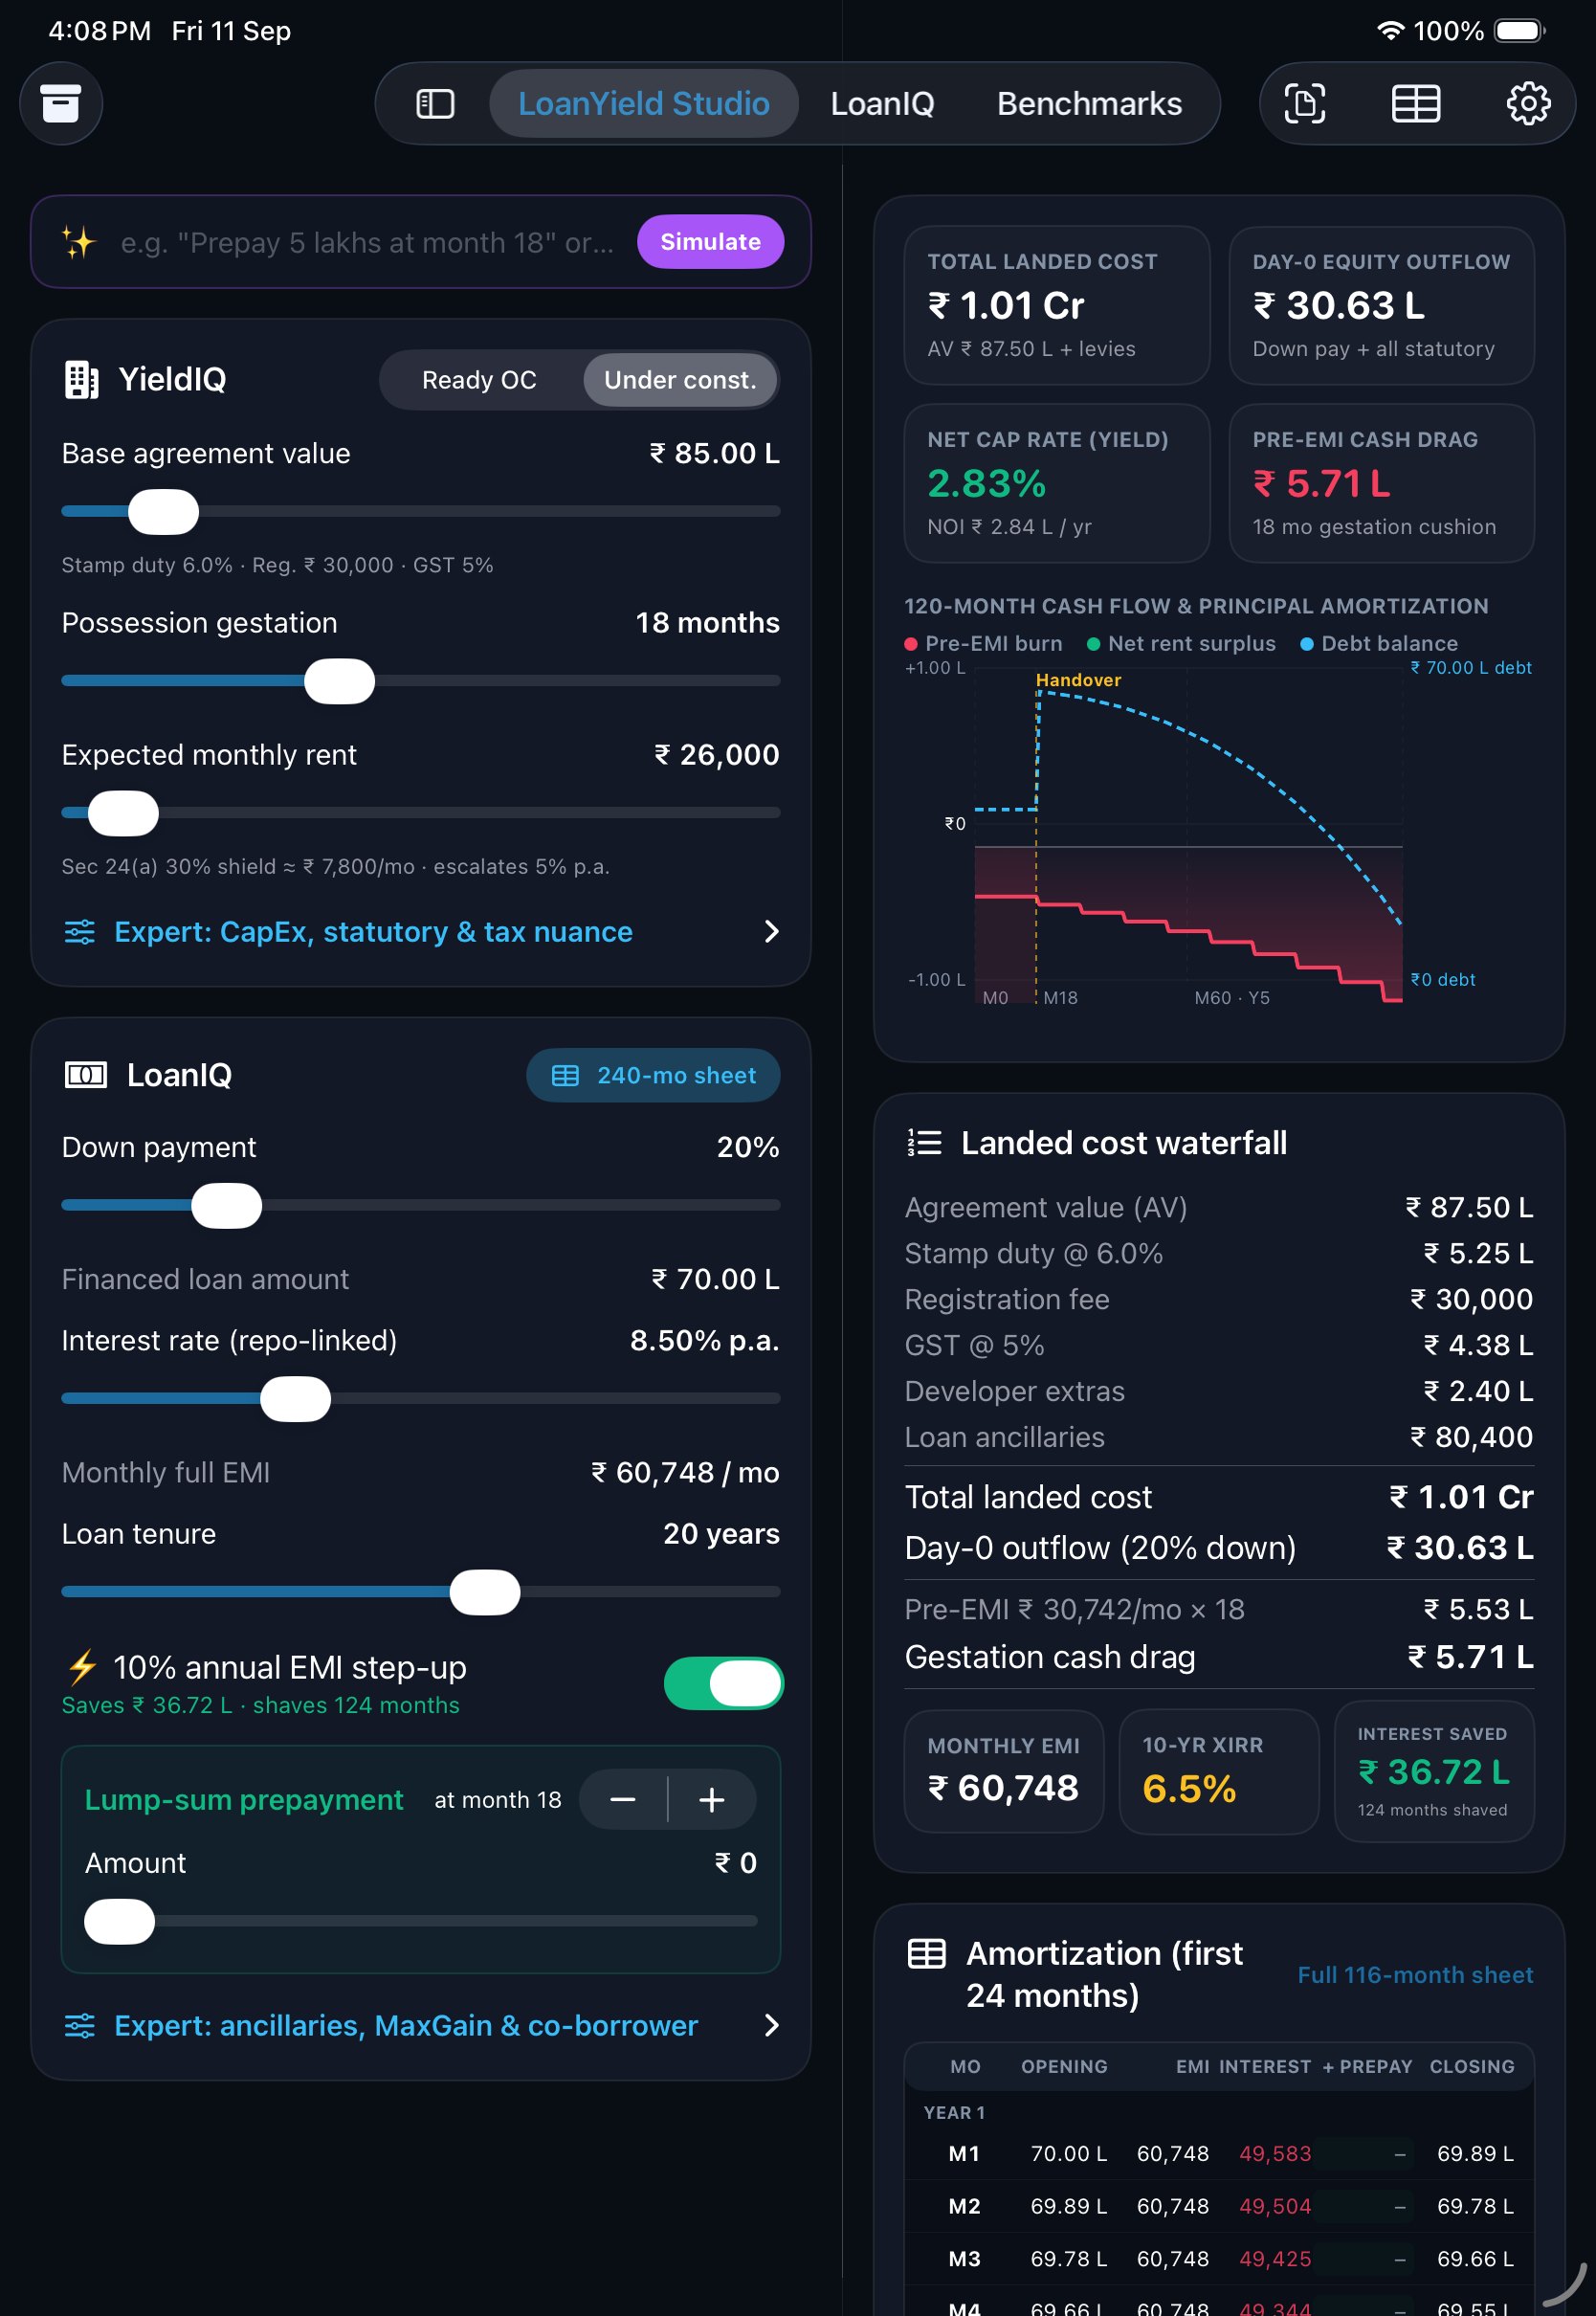
✅ A verdict, not a dashboard
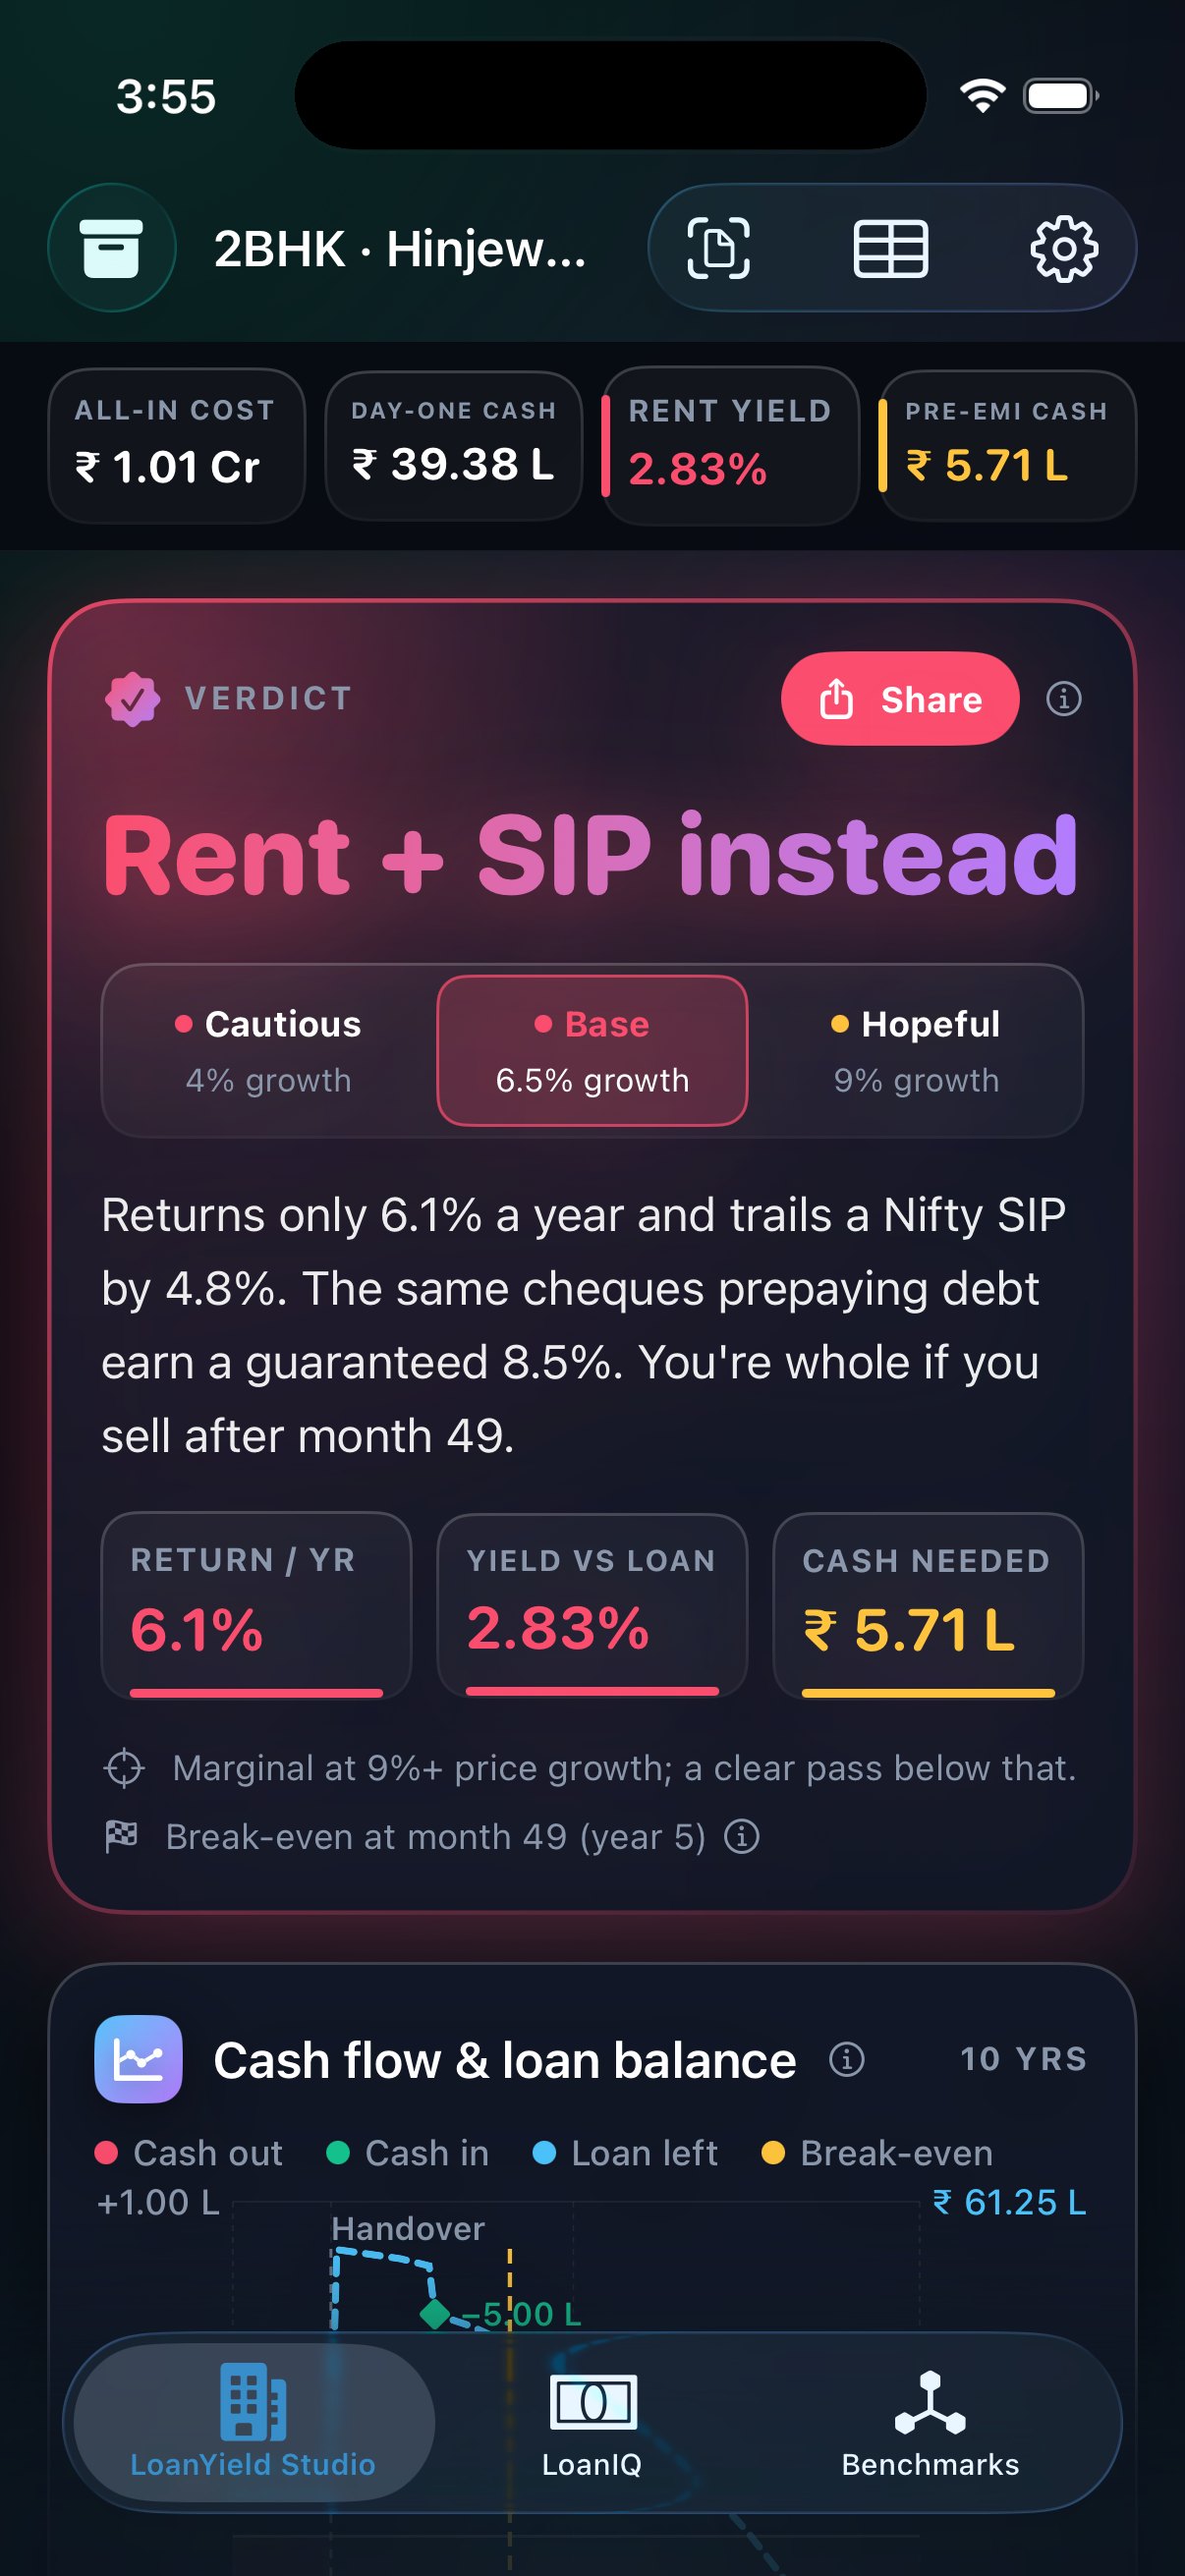
Buy · Marginal · Rent + SIP instead — with one plain-English sentence on why, the three numbers that drive it, and a colour that means something.
🎯 Three price-growth scenarios
The verdict is shown under Cautious, Base and Hopeful appreciation. If it only turns to "Buy" under Hopeful, you're betting on the market, not the flat — and the app says so.
🧾 All-in cost, state by state
Stamp duty with the women's rebate, Maharashtra's ₹30,000 registration cap, GST at 5% / 1% / 0% (18% commercial, none on land), floor rise, PLC, advance maintenance, MODT and franking. Quoted an all-in price? Toggle to it and the agreement value is backed out.
🏘️ Flat, shop or plot
Pick what you're buying. A shop gets commercial GST and a commercial loan; a plot has no GST and is modelled as bought outright — no EMI, no pre-EMI, just price growth against the alternatives.
🏗️ Under-construction economics
Months to handover, progressive disbursement, pre-EMI drag and the cash cushion you need before keys — the part every other calculator skips.
🛠️ Bare-shell? Budget the fit-out
A commercial fit-out — flooring, electrical, HVAC, ceiling — is often 15–25% of the purchase price and easy to leave out. Add it, plus brokerage as a flat fee or a %, and both land in the all-in cost and day-one cash for any loan.
🏦 A real loan model
EMI, an annual step-up you switch on and tune, one-off and recurring prepayments in any month, an optional joint-borrower cap on Section 24(b), and MaxGain-style overdraft offset.
📉 Section 24 done properly
30% standard repair deduction on net rent (24a), and by default the full interest deducted with no cap (24b) — every deal here is let-out, which is what the law actually allows. Prefer the conservative self-occupied-style ₹2 L / ₹4 L cap? One switch models that instead.
⚖️ Benchmarks & risk
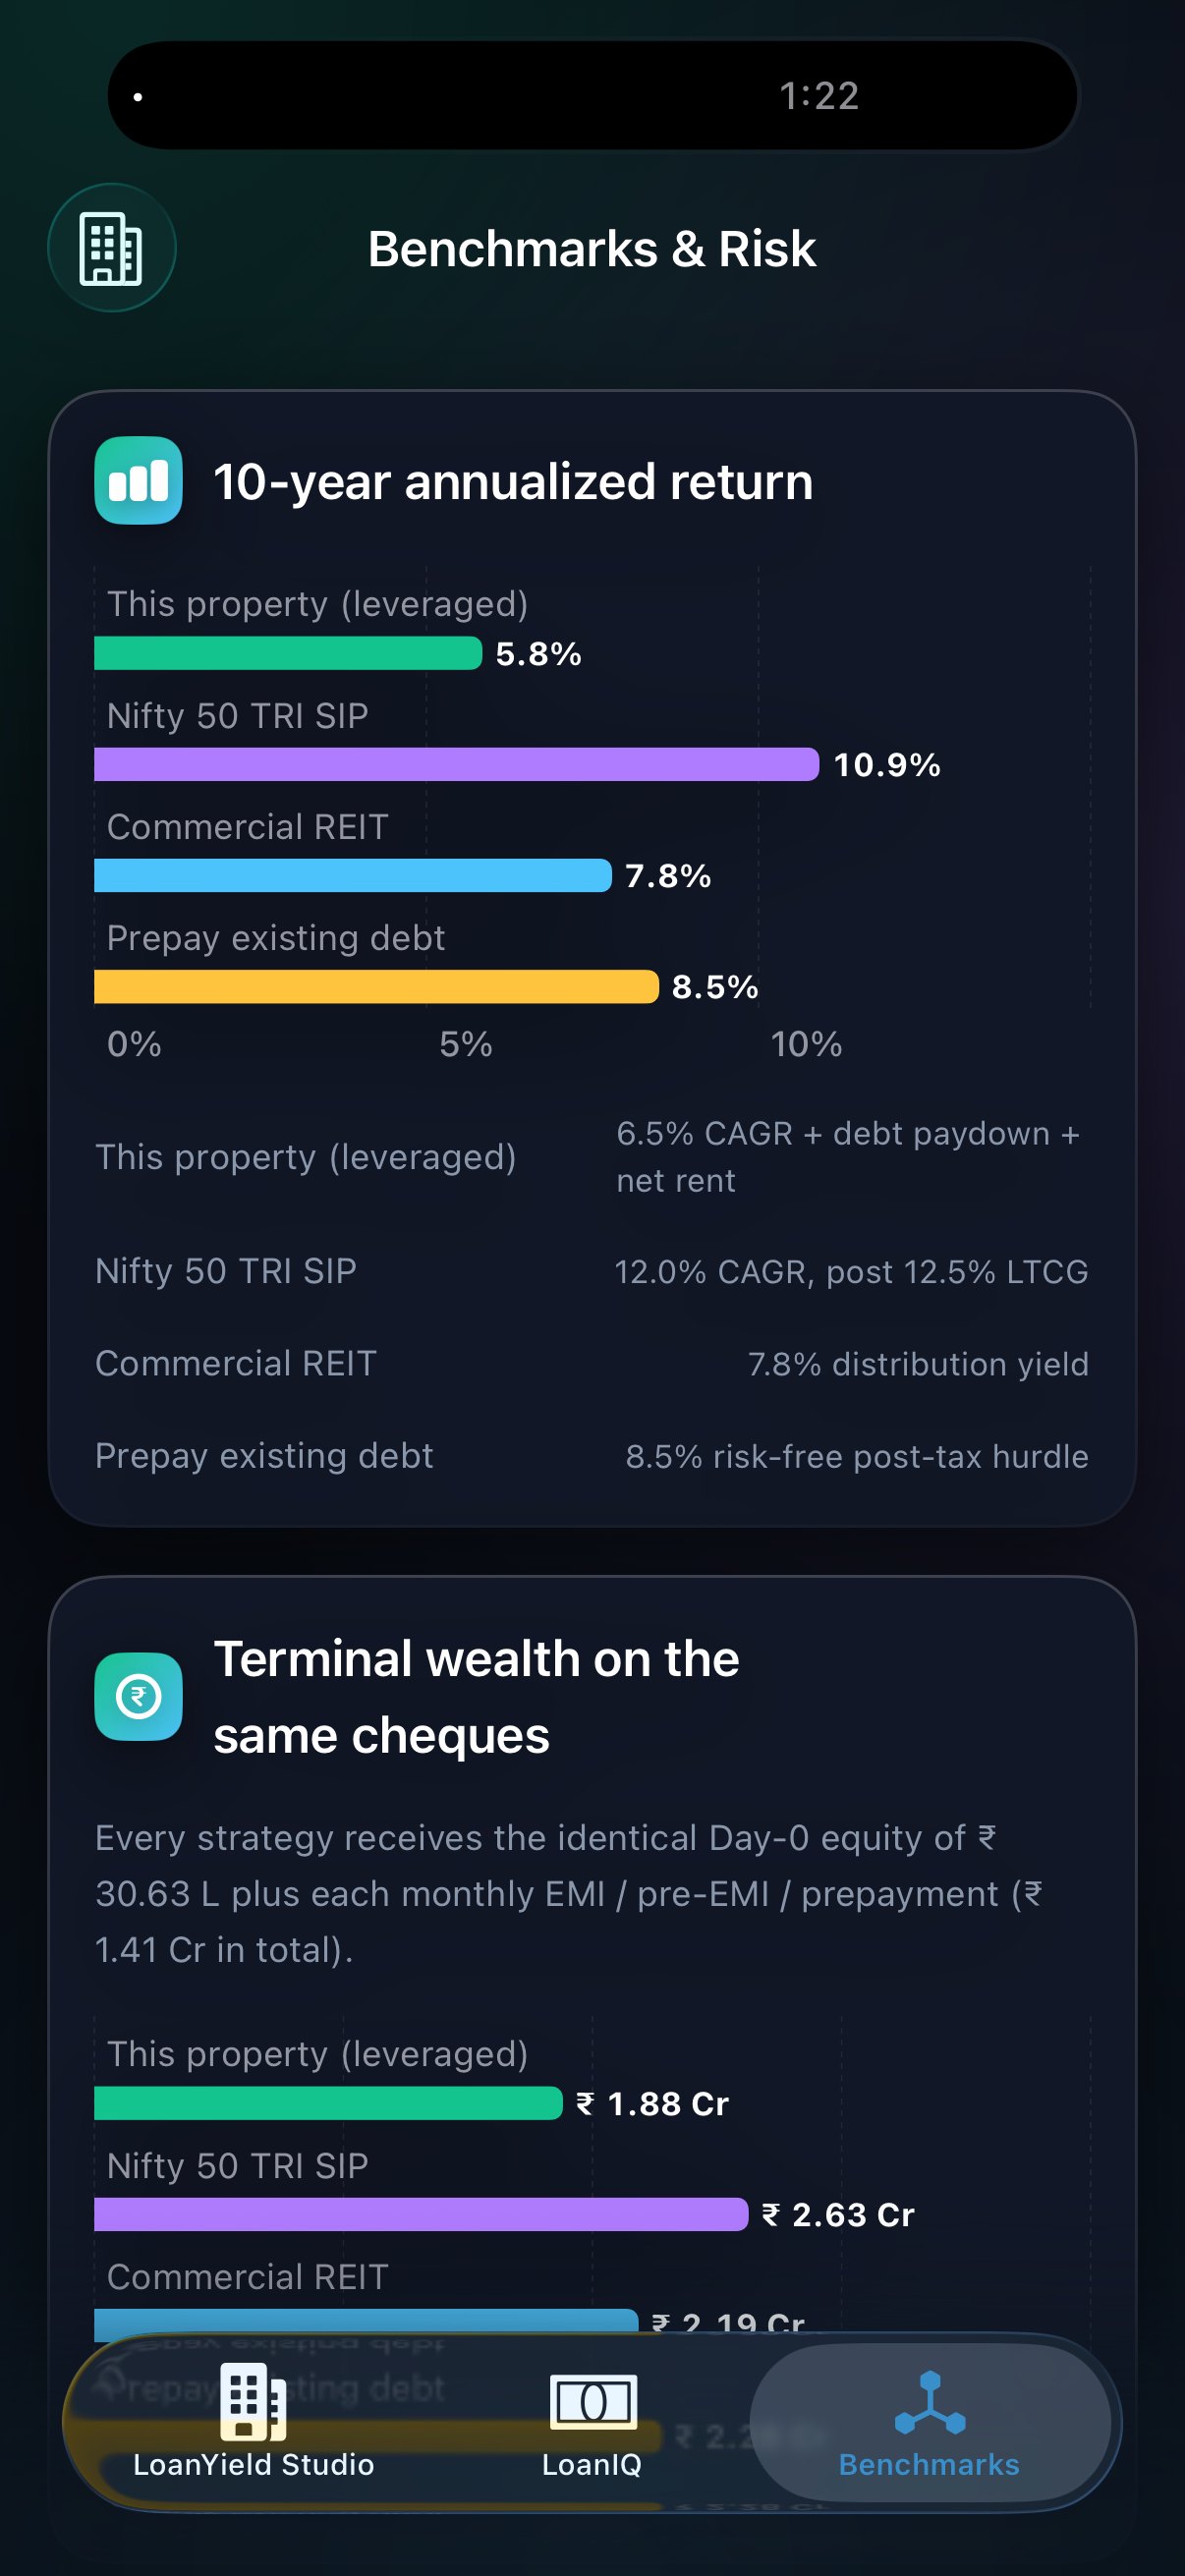
Your leveraged 10-year XIRR against the same property bought all-cash, a Nifty 50 SIP (post-LTCG), a commercial REIT, and the guaranteed return of prepaying debt — plus rate, rent, vacancy and delay shocks.
📈 Investor-grade extras
Cash-on-cash return sits right under rent yield. DSCR shows up automatically for a leveraged shop or office. And tapping the return line shows the year your XIRR actually peaks, if that's before year ten.
💬 Ask in plain English
"Prepay 5 lakhs at month 18", "50 bps hike", "delay handover 12 months" — type it or tap a chip, and every curve on screen morphs.
🔀 Compare two deals
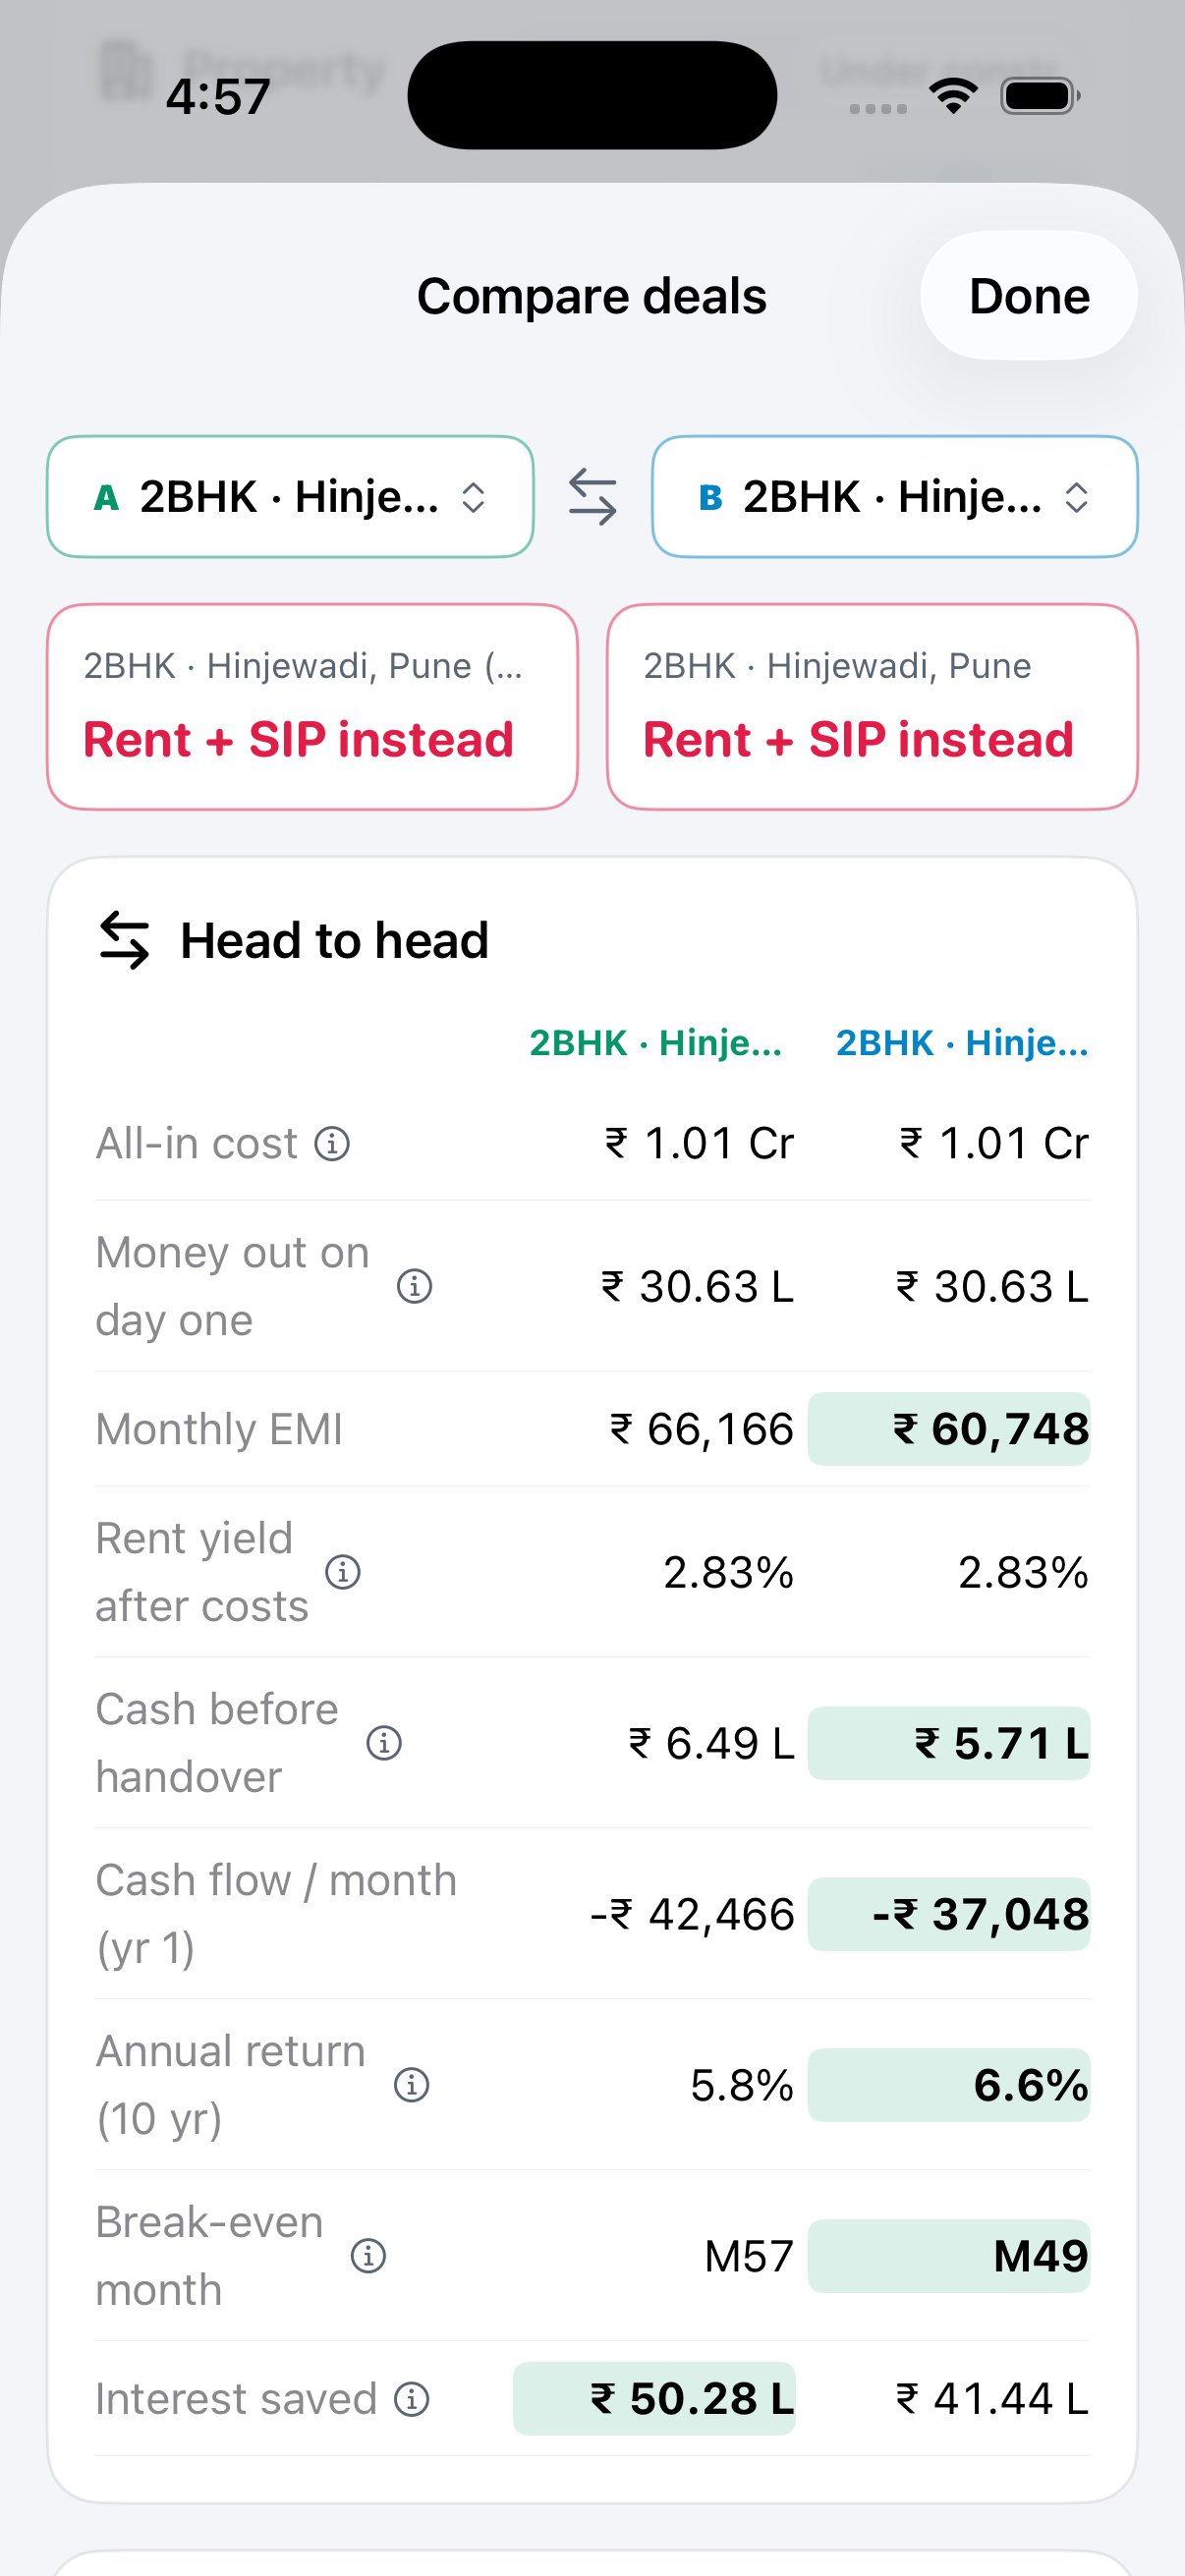
Save as many deals as you like, then put two side by side — winner highlighted on every row.
📤 Share it, two ways
A verdict card for the family WhatsApp group, or a full A4 PDF report — costs, loan, tax, ten-year cash flow, benchmarks and the complete schedule — for your CA or the bank.
📷 Import your existing loan
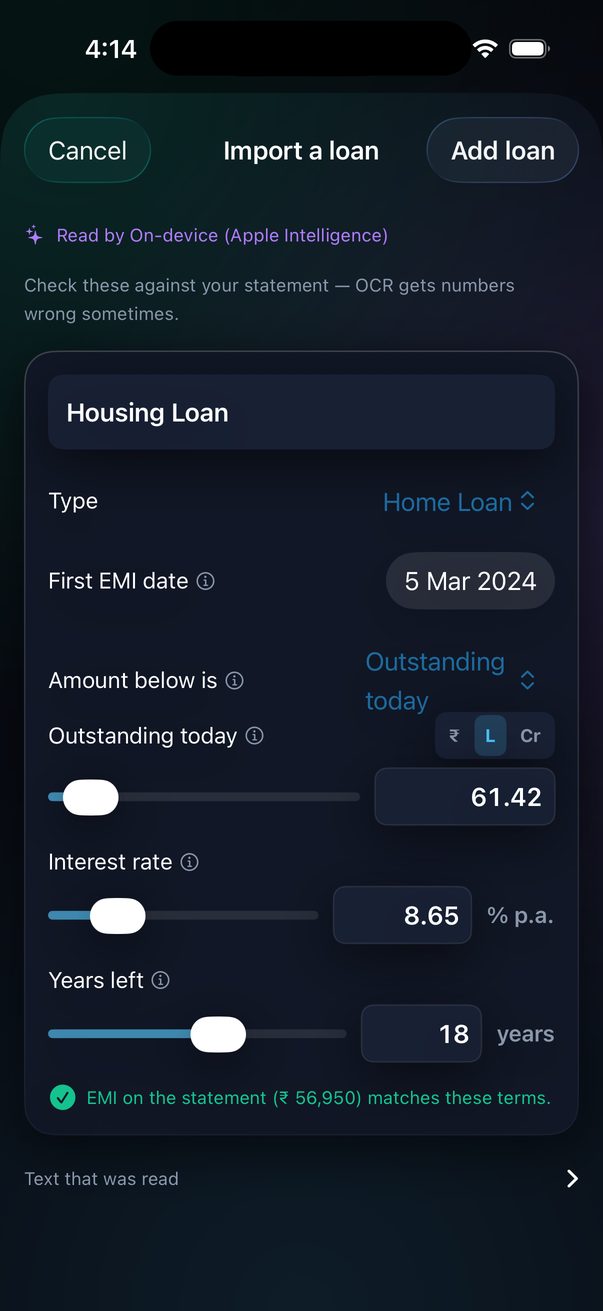
Pick a bank statement, sanction letter or amortization schedule — PDF, photo or camera scan. Headline terms are read for you; a real schedule is read row by row, so the months you've paid, any prepayments and rate resets come straight from the bank's numbers.
🧪 Plan, or just analyse
Every loan has a workspace where step-ups and prepayments are scenarios: see the interest and months saved against your saved plan, then Save it — or walk away and nothing changes. Missed a step-up one year? Pause it instead of turning it off — years before and after still count. A payoff chart and an EMI-split chart (interest vs principal, year by year) come with it, and renaming the loan is a tap at the top.
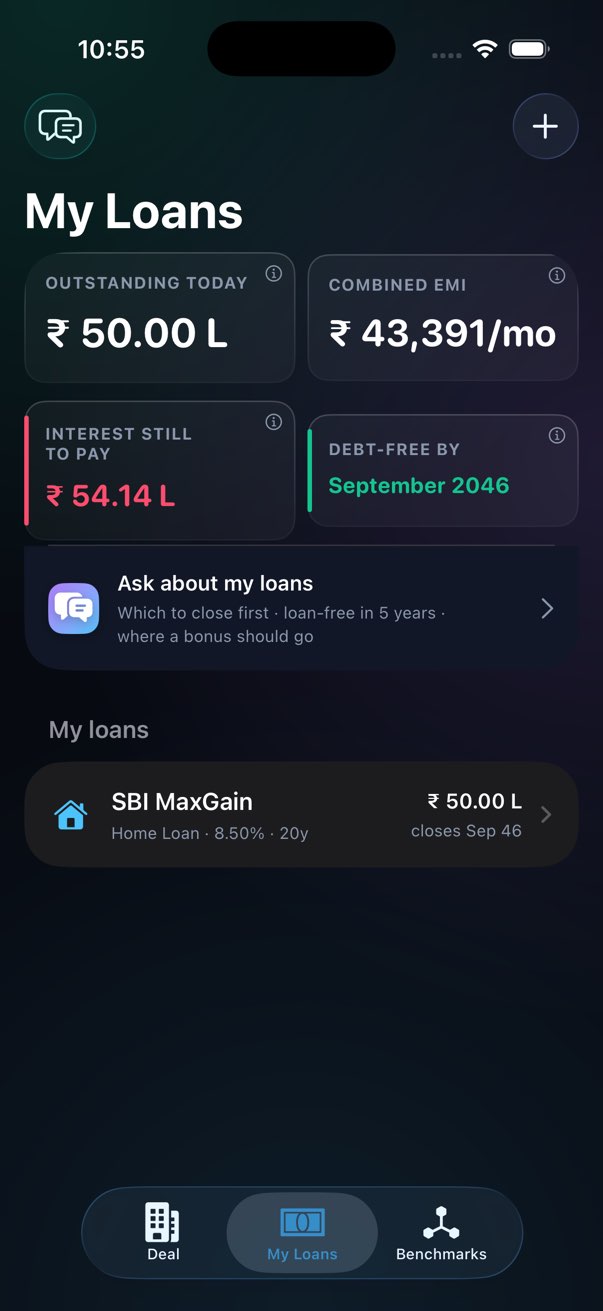
💬 Ask about your loans
"Which loan should I close first?" "Loan-free in 5 years — what does it take?" "Where should this bonus go?" A chat that answers from the amortization engine, not from a model's imagination — and works offline.
📊 One chart at a time
Cash flow, loan balance, wealth and year-by-year on tabs, each simple and scrubbable. Tap any number tile for its full label, value and explanation.
📈 RBI moved the rate. Now what?
Mark each loan floating or fixed, then apply a repo move to every floating loan in one go. See what happens if your bank keeps the EMI and stretches the tenure versus raises the EMI — combined, with a plain recommendation. On a ₹2.2 Cr two-loan example, +25 bps costs ₹4.1 L more if the EMI stays and ₹2.9 L more if it rises.
🔔 A reason to come back
Turn on reminders and each tracked loan nudges you 6, 3 and 1 month before it's debt-free, and again the month it closes — plus a periodic check-in to log a floating-rate reset. Computed and scheduled entirely on your device; off by default.
♿️ Built to be usable by everyone
VoiceOver reads every slider and money field as one labelled control, not a handful of silent parts. Charts carry a spoken summary. Text follows Dynamic Type. Colour is never the only signal, and every colour is checked against WCAG AA contrast in light and dark mode.
🔒 Free, offline, yours
All the maths runs on your phone. Data stays on the device or syncs to your own private iCloud; a JSON backup is one tap away. No account, no analytics, no ads. Ever.